Welcome to Accis

We are the voice of organisations responsibly managing data to assess the financial credibility of consumers and businesses.

ACCIS is the voice of organisations responsibly managing data to assess the financial credibility of consumers and businesses. Established as an association in 1990, ACCIS brings together more than 40 members from countries all over Europe as well as associates and affiliates across the globe.

Key Themes

What is a Credit Reference Agency?

As an industry, we enable individuals and business to take informed decisions and conduct secure, trustworthy and efficient financial operations.

Hidden

Your content goes here. Edit or remove this text inline or in the module Content settings. You can also style every aspect of this content in the module Design settings and even apply custom CSS to this text in the module Advanced settings.

What is a credit reference agency?
A credit reference agency, also known as a credit bureau, is an organisation that collects and maintains information about your credit history and financial behaviour. Credit reference agencies gather information from a variety of sources, including lenders, credit card companies, and other financial institutions, and compile this information into credit reports.
What is the main function of a credit reference agency?
The main function of a credit reference agency is to provide credit reports to lenders and other credit providers, which they can use to assess your creditworthiness and ability to repay debt. By providing accurate and reliable information, credit reference agencies help establish trust between lenders and consumers.
When were credit reference agencies created?
Credit reference agencies have been in existence for a considerable period of time. The first Credit Reference Agencies were founded in 1830 in New York and in Europe at the end of the 19th century.
What kind of data is held by credit reference agencies?
Credit reference agencies hold information, such as your identification data (name, date of birth, address,
and a unique identification number if this is legally allowed) and data concerning your credit history e.g., if you own a bank account or a credit card or have payment defaults. They can also hold other public records e.g., information on bankruptcies, foreclosures, etc. Credit reference agencies do not hold information on what you earn, your nationality,your employment, or other sensitive personal data (e.g., religion, political preferences, gender).
What is a credit report?
A credit report is a document that provides information about your credit history and financial behaviour. It is compiled by credit reference agencies, which gather information from a variety of sources, including lenders, credit card companies, and other financial institutions. Creditors use credit reports to make creditrelated decisions.
What is a positive credit history?
A positive credit history is one that shows your ability to manage credit properly through a track record of responsible borrowing and repayment behaviour. It is an essential factor in determining your creditworthiness and can influence your ability to obtain credit or loans, as well as the interest rates given. Examples of positive data are fully paid credit cards, timely payments, length of credit history, paid mail order invoices and non-arrear bank accounts
What is a negative credit history?
A negative credit history is a record of your past borrowing and repayment behaviour that suggests your inability or unwillingness to manage your credit responsibly. Examples of negative credit history are late payments, defaults, high credit utilisation, bankruptcies and /or insolvencies.
Hidden

Your content goes here. Edit or remove this text inline or in the module Content settings. You can also style every aspect of this content in the module Design settings and even apply custom CSS to this text in the module Advanced settings.

What is a credit score?
A credit score is a numerical representation of your creditworthiness, based on your credit history and other financial behavior. Credit scores are typically calculated by credit reference agencies, using a range of factors such as payment history, credit utilization, length of credit history, and types of credit. Credit scores are just one factor that lenders consider when making credit decisions. They may also take into account other factors such as your income, employment status, and debt-to-income ratio.
Are credit reference agencies regulated?
Yes. National regulations define the legal environment in which credit reference agencies operate. The law also defines the scope of data credit reference agencies can hold and for how long they can store your data. Credit reference agencies are also subject to the provisions of banking laws and other local regulations.
Who uses the services of credit reference agencies?
The most common users of credit reference agencies’ services are banks and non-banking financial
companies, but also telecommunication, insurance, mail order, and /or utility companies. The types of clients that use the services of credit reference agencies vary from country to country and depend on the legal environment of the country.
How do credit reference agencies help lenders?
CRAs help lenders to accurately assess your credit eligibility because the information that is managed by the CRAs proves your credibility and creditworthiness
How do credit reference agencies help you?
Credit reference agencies play an important role in helping you access credit. When you apply for credit, lenders can quickly and easily check your credit report to see if you have a history of paying bills on time and managing credit responsibly. They can also help verify your identity by checking your personal information against public records and other sources. This can help prevent identity theft and other types of fraud. Credit reference agencies can also help prevent fraud by flagging suspicious activity on your credit report, such as new accounts that were opened without your knowledge. Finally, credit reference agencies can provide you with financial education, that will help you manage your finances more effectively.
What right rights do you have when you deal with credit reference agencies?
You have several rights when dealing with credit reference agencies. These rights include the right to access your credit report – so that you know what personal information the credit reference agency holds about you – and the right to dispute inaccurate information and add a notice of correction – so that you can ensure that any inaccurate or outdated information is deleted from your credit report.
Does having a credit report or a good credit score automatically mean you will be granted credit?
No. Credit reports and credit scores are an input in the lender’s decision-making process. It is up to the lender – after a thorough internal risk analysis – to make the ultimate decision whether to grant you the credit or not.

Trusted by
Collaborating with

News

ACCIS Brussels Policy Roundtable 2026, 19 November 2026, 15:30 to 18:30 CET, Spa30, Brussels

ACCIS Policy event on Digital Omnibus in Brussels – 19 November

ACCIS has organised an in-person policy event on 19 November since the Digital Omnibus has reignited a discussion on, among other topics, automated decisions under the GDPR. While the EU Member States will essentially negotiate to maintain the status quo on automated...
ACCIS Webinar: Buy Now Pay Later, 12 November 2026, 16:00 to 17:30 CET, online

Members’ Webinar on Buy Now Pay Later – 12 November

Join us for a fascinating exchange on BNPL quite literally around the world! Date: 12 November Time: 16:00 – 17:30 CET Speakers from: ACCIS Research Working Committee, Brazil, South Africa, UK and USA! What began as a mapping exercise in the ACCIS Research Working...

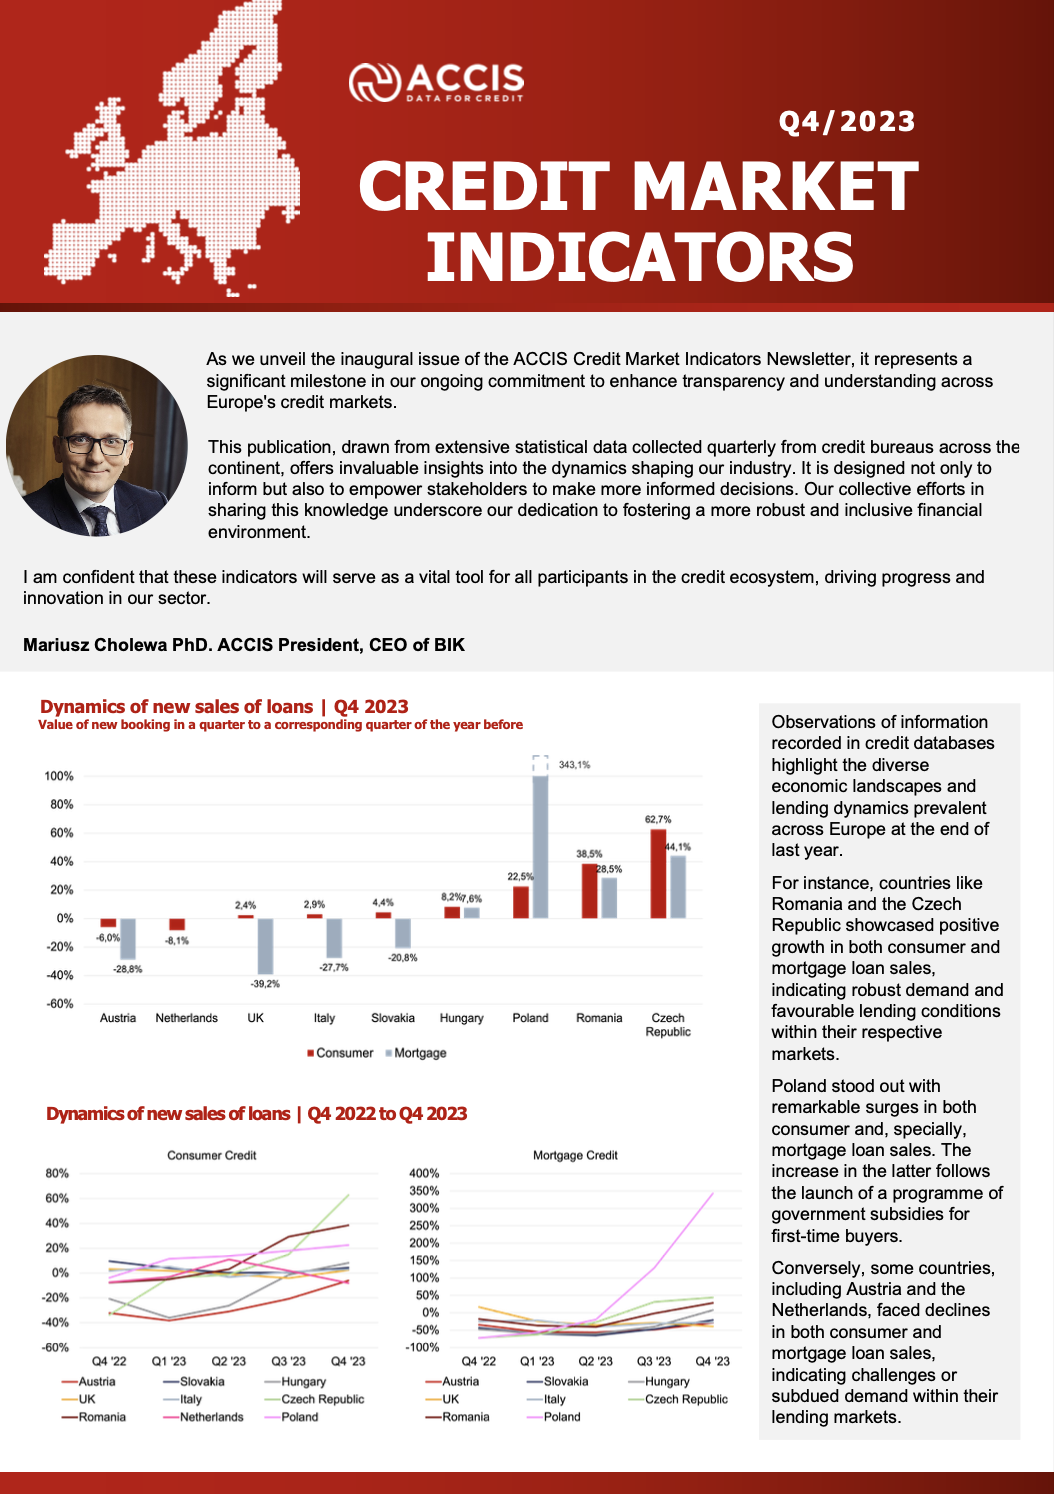
ACCIS publishes the Q1 2026 edition of the Credit Market Indicators Newsletter

ACCIS has published the Q1 2026 edition of the ACCIS Credit Market Indicators Newsletter. At the heart of this quarterly newsletter lies a wealth of data curated from reports furnished by credit bureaus spanning the European continent, giving stakeholders insights...
ACCIS publishes the Q4 2025 edition of the Credit Market Indicators Newsletter

ACCIS has published the Q4 2025 edition of the ACCIS Credit Market Indicators Newsletter. At the heart of this quarterly newsletter lies a wealth of data curated from reports furnished by credit bureaus spanning the European continent, giving stakeholders insights...
ACCIS publishes the Q3 2025 edition of the Credit Market Indicators Newsletter

ACCIS has published the Q3 2025 edition of the ACCIS Credit Market Indicators Newsletter. At the heart of this quarterly newsletter lies a wealth of data curated from reports furnished by credit bureaus spanning the European continent, giving stakeholders insights...
ACCIS publishes the Q2 2025 edition of the Credit Market Indicators Newsletter

ACCIS has published the Q2 2025 edition of the ACCIS Credit Market Indicators Newsletter. At the heart of this quarterly newsletter lies a wealth of data curated from reports furnished by credit bureaus spanning the European continent, giving stakeholders insights...
ACCIS publishes the Q1 2025 edition of the Credit Market Indicators Newsletter

ACCIS has published the Q1 2025 edition of the ACCIS Credit Market Indicators Newsletter. At the heart of this quarterly newsletter lies a wealth of data curated from reports furnished by credit bureaus spanning the European continent, giving stakeholders insights...
ACCIS publishes the Q4 2024 edition of the Credit Market Indicators Newsletter

ACCIS has published the Q4 2024 edition of the ACCIS Credit Market Indicators Newsletter. At the heart of this quarterly newsletter lies a wealth of data curated from reports furnished by credit bureaus spanning the European continent, giving stakeholders insights...

ACCIS publishes the Q3 2024 edition of the Credit Market Indicators Newsletter

ACCIS has published the Q3 2024 edition of the ACCIS Credit Market Indicators Newsletter. At the heart of this quarterly newsletter lies a wealth of data curated from reports furnished by credit bureaus spanning the European continent, giving stakeholders insights...

ACCIS publishes the Q2 2024 edition of the Credit Market Indicators Newsletter

ACCIS has published the Q2 2024 edition of the ACCIS Credit Market Indicators Newsletter. At the heart of this quarterly newsletter lies a wealth of data curated from reports furnished by credit bureaus spanning the European continent, giving stakeholders insights...

Position Papers

ACCIS responds to Commission consultation on high-risk AI classification guidelines

ACCIS has submitted its contribution to the European Commission's stakeholder consultation on the draft Guidelines on the classification of high-risk AI systems under Article 6 of the AI Act, which closed on 23 July 2026. In its response, ACCIS calls on the Commission...

ACCIS provides feedback on proposed amendments to GDPR via Digital Omnibus package

The European Commission's Digital Omnibus package (published 19 November, 2025; see here) proposes a number of amendments to inter alia the GDPR, including to Article 22. Recognising the significance of these proposals for the credit information sector, ACCIS engaged...

Public Consultation on the Digital Fitness Check

The digital fitness check is the second stage of the Commission's plan to simplify the EU's digital rules, following the adjustments proposed under the Digital Omnibus. Its aim is to ensure that the EU's digital rules are effective, proportionate and fit for the...

ACCIS contributes input into the European Commission’s Call For Evidence on the Digital Omnibus

The Digital package on simplification, which is scheduled for release on 19 November, is a flagship initiative of this Commission that is meant to bring to life its commitment to reducing the regulatory burden on businesses in the sphere of digital policy. In ACCIS’s...

ACCIS provides a response to the European Commission’s public consultation on the Digital Fairness Act

ACCIS appreciates the framing of the consultation questionnaire in the sense that it openly asks stakeholders whether and how consumer laws can be simplified in order to reduce the burden for businesses while maintaining the same level of consumer protection. In that...

ACCIS response to the European Commission’s public consultation on high-risk AI systems

In our response we explain that credit information suppliers are using AI for a number of different use cases ranging from KYC and anti-fraud processes, data filtering (not high-risk) all the way to producing credit scores (high-risk). At the same time, we underline...

ACCIS input into the CNIL Consultation on its reference framework for credit and the treatment of personal data.

ACCIS provided input into the French Data Protection Authority – CNIL – consultation on a reference framework for credit, “Un projet de référentiel sur l’octroi de crédit” due to the importance of the topic and the contribution made by the French DPA. This is despite...

ACCIS response to consultation on European Commission’s guidelines for an AI system definition

In our response, ACCIS argues that logistic regression (LR) is a simple statistical method distinct from artificial intelligence (AI) and should not be regulated as such under the AI Act. Unlike AI, LR lacks advanced capabilities like learning, reasoning, or complex...

ACCIS response to the EDPB’s Guidelines 1/2024 on processing of personal data based on Article 6(1)(f) GDPR – Legitimate interest

In our response to the EDPB Guidelines on legitimate interest, we highlight areas of agreement as well as sections where further clarification or amendment may be beneficial to ensure a balanced application of legitimate interest provisions in the context of consumer...

ACCIS response to targeted consultation on AI in financial services

In our response, ACCIS notes that credit reference agencies are exploring the use of AI to help lenders evaluate the creditworthiness of individuals and businesses, as well as to establish credit scores. We highlight that AI's ability to analyse vast and complex...

ACCIS on LinkedIn